10 Budgeting Mistakes Costing Americans Thousands
Discover 10 budgeting mistakes costing Americans thousands each year and learn practical fixes to save more, reduce debt, and build lasting wealth.

10 Budgeting Mistakes Costing Americans Thousands

Budget problems do not always begin with one enormous purchase. More often, financial pressure develops through smaller mistakes repeated month after month: underestimated spending, forgotten annual bills, expensive credit card balances, lifestyle inflation, or a budget that never gets updated.
Those mistakes can become expensive over time.
For example, spending an unnecessary $200 each month represents $2,400 over one year and $12,000 over five years before considering any interest or investment returns that money might otherwise have generated.
The latest Federal Reserve household survey also shows why relatively small budget mistakes can matter. In 2025, 63% of U.S. adults said they could cover a hypothetical $400 emergency expense entirely with cash, savings, or a credit card paid in full at the next statement. The remaining 37% said they would need another method or could not cover the expense that way.
The goal of budgeting is therefore not to account for every dollar perfectly. It is to create enough financial margin that routine expenses, irregular bills, and unexpected costs do not repeatedly force you into new debt.
Mistake #1: Guessing How Much You Spend
One of the most common budgeting errors is building a spending plan around estimates rather than actual transactions.
You may believe groceries cost $500 per month when the real average is $675. You may estimate $150 for restaurants while actual spending regularly exceeds $300.
Small differences across several categories can create a large gap between your planned budget and reality.
How to Fix It
Review at least the previous two or three months of checking-account and credit-card transactions.
Separate spending into categories such as:
- Housing
- Utilities
- Groceries
- Transportation
- Insurance
- Debt payments
- Restaurants
- Shopping
- Subscriptions
Use the average of actual spending as the starting point for your next budget instead of choosing an amount based on memory.
Mistake #2: Ignoring Irregular Expenses
A budget can appear balanced every month while still running at a deficit over the full year.
The reason is often irregular expenses.
Examples include:
- Annual insurance premiums
- Vehicle registration
- Car maintenance
- Home repairs
- Medical expenses
- School costs
- Holiday spending
- Travel
- Annual subscriptions
These costs may not arrive every month, but they are still part of your financial life.
How to Fix It
Estimate the annual amount of predictable irregular expenses and divide the total by 12.
For example, suppose you expect:
| Irregular Expense | Annual Estimate |
|---|---|
| Car maintenance | $1,200 |
| Insurance premium | $900 |
| Holiday spending | $600 |
| Home repairs | $900 |
| Total | $3,600 |
Dividing $3,600 by 12 gives approximately $300 per month.
Setting aside that amount regularly can make future bills less disruptive.
Mistake #3: Ignoring Small Recurring Purchases
Small purchases are not automatically bad. The problem occurs when they are frequent enough to materially affect your budget but small enough to escape attention.
Suppose someone spends $12 on lunch during 250 workdays in a year.
$12 × 250 = $3,000 per year
The issue is not that buying lunch is financially irresponsible.
The point is that seemingly minor recurring decisions can become major annual expenses.
| Recurring Spending | Monthly Cost | Annual Cost |
|---|---|---|
| $5 per day | About $150 | About $1,825 |
| $10 per day | About $300 | About $3,650 |
| $15 per day | About $450 | About $5,475 |
Reviewing these expenses gives you the choice to keep them, reduce them, or redirect some of the money toward another financial priority.
Mistake #4: Saving Only Whatever Is Left at the End of the Month

Saving whatever remains after every other purchase can make contributions inconsistent.
Discretionary spending often expands to use available cash.
A more structured approach is to decide on a realistic savings amount before the month is over.
How to Fix It
Consider scheduling an automatic transfer shortly after payday.
The amount does not need to be large.
Someone beginning with $25 every two weeks would contribute:
$25 × 26 = $650 per year
A $100 biweekly contribution would equal $2,600 over 26 paychecks.
The appropriate amount depends on income, expenses, debt, and existing savings.
Mistake #5: Paying Only the Credit Card Minimum
Minimum payments keep an account current, but they can allow a balance to remain outstanding for many years.
Credit card interest rates can make this especially expensive.
A borrower should review the minimum-payment warning on the monthly credit card statement, which generally shows how long repayment could take and how much could be paid if only minimum payments are made.
The higher the APR and the longer a balance remains outstanding, the greater the potential interest cost.
How to Fix It
Continue making at least all required minimum payments, then evaluate whether additional cash can be directed toward debt.
One strategy is the debt avalanche, which directs additional payments toward the highest-interest balance first.
Another is the debt snowball, which prioritizes the smallest balance.
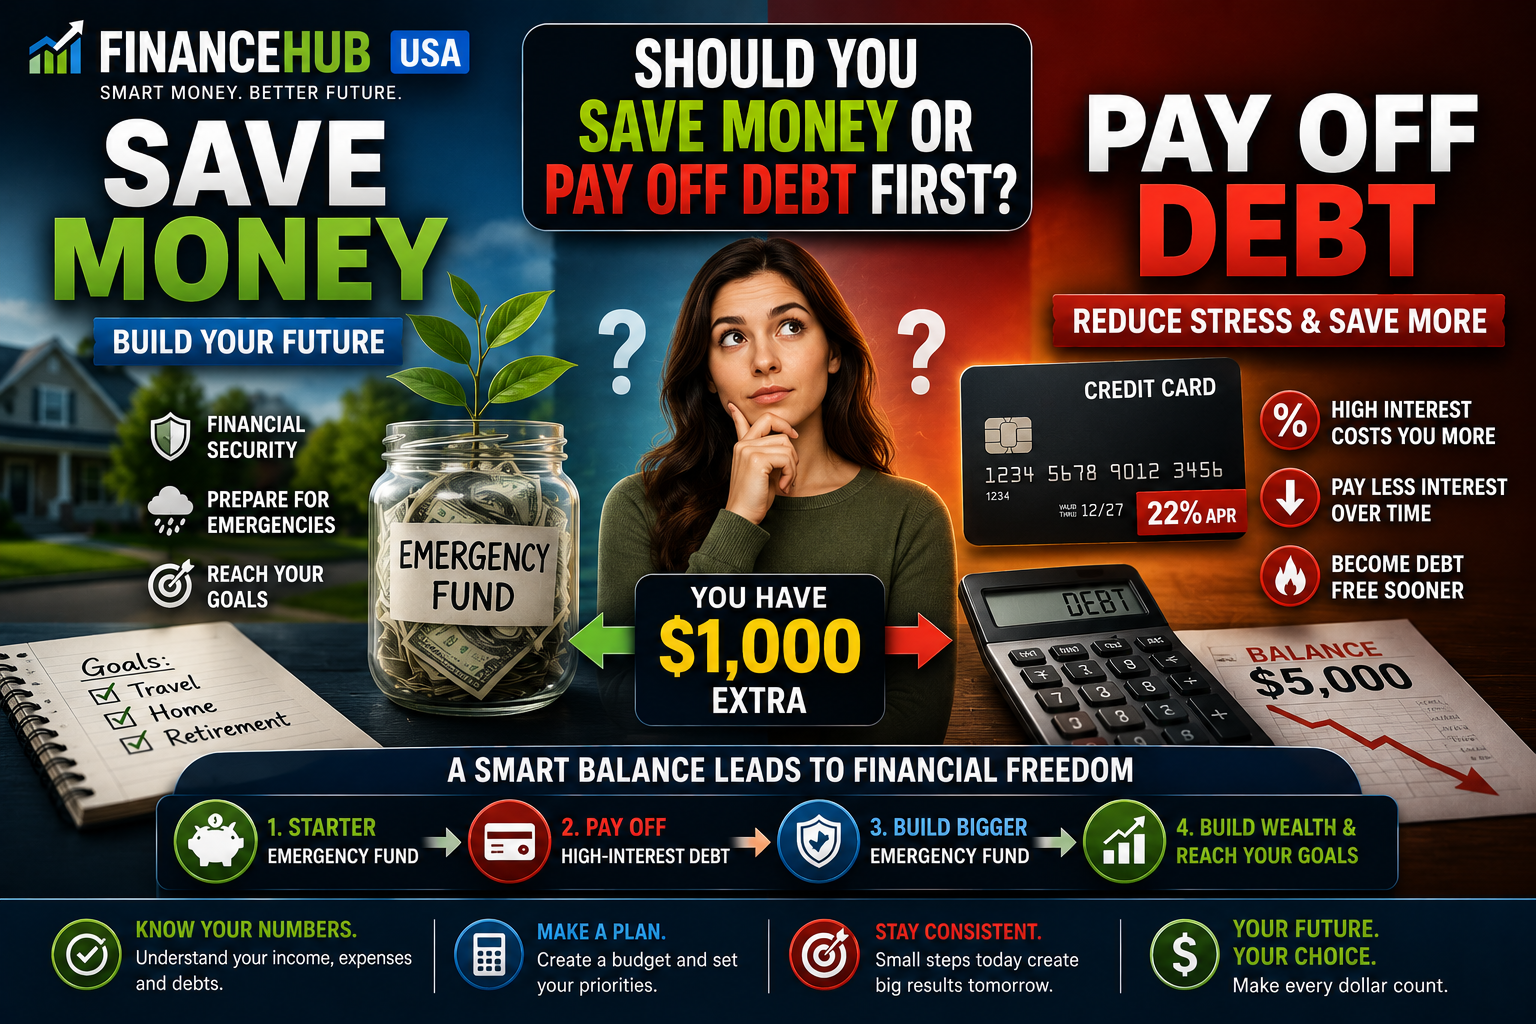
For a deeper comparison, see Should You Save Money or Pay Off Debt First?
Mistake #6: Having No Emergency Savings
An unexpected car repair, medical bill, home repair, or income disruption can create new debt when no cash reserve exists.
The Federal Reserve's 2025 household survey found that 55% of adults had savings specifically set aside to cover three months of expenses.
That also means a substantial share of households did not have that level of dedicated emergency savings.
There is no universal emergency-fund amount appropriate for everyone.
The amount depends on:
- Essential monthly expenses
- Income stability
- Household size
- Insurance coverage
- Dependents
- Health needs
- Access to other financial resources
How to Fix It
If you are starting from zero, focus first on building an amount that can absorb some of the unexpected expenses your household is most likely to face.
Then increase the reserve gradually as cash flow permits.
The Federal Reserve reported that the most common unexpected expenses experienced by households included major vehicle repairs or replacement, home or appliance repairs, and major medical expenses.
Mistake #7: Allowing Every Raise to Become New Spending
Income growth does not automatically improve financial security.
If spending rises by the same amount as income, the household's financial margin may remain unchanged.
This is commonly called lifestyle inflation.
Suppose take-home pay increases by $400 per month.
| Use of Raise | Monthly Amount | Annual Amount |
|---|---|---|
| Additional lifestyle spending | $400 | $4,800 |
| Save $100 and spend $300 | $100 saved | $1,200 saved |
| Save $200 and spend $200 | $200 saved | $2,400 saved |
There is no rule requiring a particular percentage of every raise to be saved.
The opportunity is simply to decide how much of the additional income should improve your financial position before new spending habits absorb the entire increase.
Mistake #8: Looking Only at Monthly Payments
A monthly payment can make an expensive purchase appear affordable.
This is especially common with vehicles, loans, and financing offers.
But the monthly payment alone does not show the total financial commitment.
For transportation, total costs can include:
- Loan payment
- Insurance
- Fuel
- Maintenance
- Repairs
- Registration
- Parking
- Depreciation
Housing has similar additional expenses beyond rent or mortgage principal and interest.
How to Fix It
Estimate the total monthly and annual cost before committing to a major recurring expense.
A budget should evaluate affordability based on the entire financial obligation rather than one advertised payment.
Mistake #9: Creating a Budget and Never Updating It

A budget represents your finances at a particular point in time.
Income and expenses change.
Rent increases. Insurance premiums change. Grocery spending changes. Debt gets paid off. Children create new expenses. Raises increase income.
A budget created months ago can therefore stop reflecting reality.
How to Fix It
Review your budget periodically and compare planned spending with actual spending.
A simple monthly review can include:
- Total take-home income
- Total spending
- Amount saved
- Debt balances
- Upcoming irregular expenses
- Changes in recurring bills
You do not need to rebuild the entire budget every month.
The purpose is to identify significant differences early.
Mistake #10: Creating a Budget That Is Too Restrictive to Maintain
A budget that eliminates every optional purchase may look impressive on paper but can be difficult to sustain.
For example, a household accustomed to spending $500 per month on restaurants, hobbies, and entertainment may struggle to move immediately to zero.
A more sustainable budget acknowledges discretionary spending while setting limits that are compatible with larger financial priorities.
How to Fix It
Create a defined discretionary category.
The amount should fit within the household's overall financial situation rather than follow an arbitrary percentage.
A sustainable plan is generally more useful than an extreme budget that lasts only a few weeks.
How Much Can Budgeting Mistakes Really Cost?
The word "thousands" can sound exaggerated until recurring expenses are converted into annual numbers.
| Monthly Budget Leak | 1-Year Cost | 5-Year Cost |
|---|---|---|
| $50 | $600 | $3,000 |
| $100 | $1,200 | $6,000 |
| $200 | $2,400 | $12,000 |
| $300 | $3,600 | $18,000 |
| $500 | $6,000 | $30,000 |
Figures show simple accumulated spending and exclude inflation, interest, investment returns, and changes in spending.
The point is not that every dollar of discretionary spending is a mistake.
The problem is money leaving the budget without providing enough value or without being recognized in the financial plan.
FinanceHub USA Analysis: The Most Important Number Is Your Financial Margin
Many budgeting discussions focus almost entirely on individual categories.
But one of the most useful measurements is the difference between what you take home and what you spend.
Financial margin = Take-home income − Total expenses
You can also express it as a percentage:
Financial margin percentage = (Money left after expenses ÷ Take-home income) × 100
Consider two households earning the same $5,000 in monthly take-home pay.
| Household A | Household B | |
|---|---|---|
| Take-home income | $5,000 | $5,000 |
| Monthly expenses | $4,850 | $4,000 |
| Money remaining | $150 | $1,000 |
| Financial margin | 3% | 20% |
Their incomes are identical, but their ability to absorb unexpected expenses is very different.
This is why correcting multiple small budgeting mistakes can matter even if no individual change feels dramatic.
A 30-Day Budget Reset
A budget does not need to be rebuilt overnight.
A simple four-week process can make the task more manageable.
Week 1: Measure
- Review the previous 60 to 90 days of transactions.
- Calculate average spending by category.
- Identify recurring charges.
Week 2: Add the Expenses You Forgot
- List annual and irregular expenses.
- Estimate their annual cost.
- Convert them into monthly amounts.
Week 3: Identify Priorities
- Review emergency savings.
- Review high-interest debt.
- Choose a sustainable savings amount.
- Cancel recurring expenses that no longer provide sufficient value.
Week 4: Automate and Review
- Automate savings where appropriate.
- Schedule required payments.
- Check upcoming irregular expenses.
- Compare the new budget with actual cash flow.
How to Know Whether Your Budget Is Improving
Do not measure success only by whether every category stayed under its target.
Look for broader improvements.
| Indicator | Possible Sign of Improvement |
|---|---|
| Financial margin | Increasing over time |
| Emergency savings | Growing consistently |
| High-interest debt | Declining |
| Irregular expenses | Funded before they arrive |
| Credit card reliance | Less borrowing for routine expenses |
Common Budgeting Myths
You Must Follow One Specific Percentage Rule
Budgeting frameworks such as the 50/30/20 approach can provide a useful starting point, but household expenses differ substantially.
A percentage should be treated as a planning tool rather than a financial law.
Every Small Purchase Must Be Eliminated
A sustainable budget does not require removing everything enjoyable.
The objective is intentional spending.
A Higher Income Automatically Solves Budget Problems
Higher income can help, but financial pressure can remain if spending rises just as quickly.
Budgeting Is Only for People in Financial Trouble
A budget can also help households with strong cash flow decide how much to save, invest, spend, or allocate toward future goals.
Final Thoughts
The most expensive budgeting mistakes are often ordinary habits repeated for months or years.
Guessing at expenses, ignoring annual bills, carrying expensive debt, having no emergency reserve, allowing lifestyle spending to absorb every raise, and failing to update the budget can collectively cost thousands of dollars.
The Federal Reserve's latest household survey shows that financial resilience remains uneven. While 63% of adults could cover a $400 unexpected expense with cash or its equivalent in 2025, many households would need another approach, and only 55% reported having a dedicated rainy-day fund sufficient for three months of expenses.
A useful budget does not need to be perfect.
It needs to reflect real spending, anticipate predictable expenses, protect important financial priorities, and leave enough flexibility to remain sustainable.
The most important improvement may be gradually increasing the gap between what your household earns and what it needs to spend.
Continue exploring FinanceHub USA for practical guides on budgeting, saving, debt, credit, emergency funds, and everyday personal finance.
Related reading: How Much Money Should You Have Left After Bills?
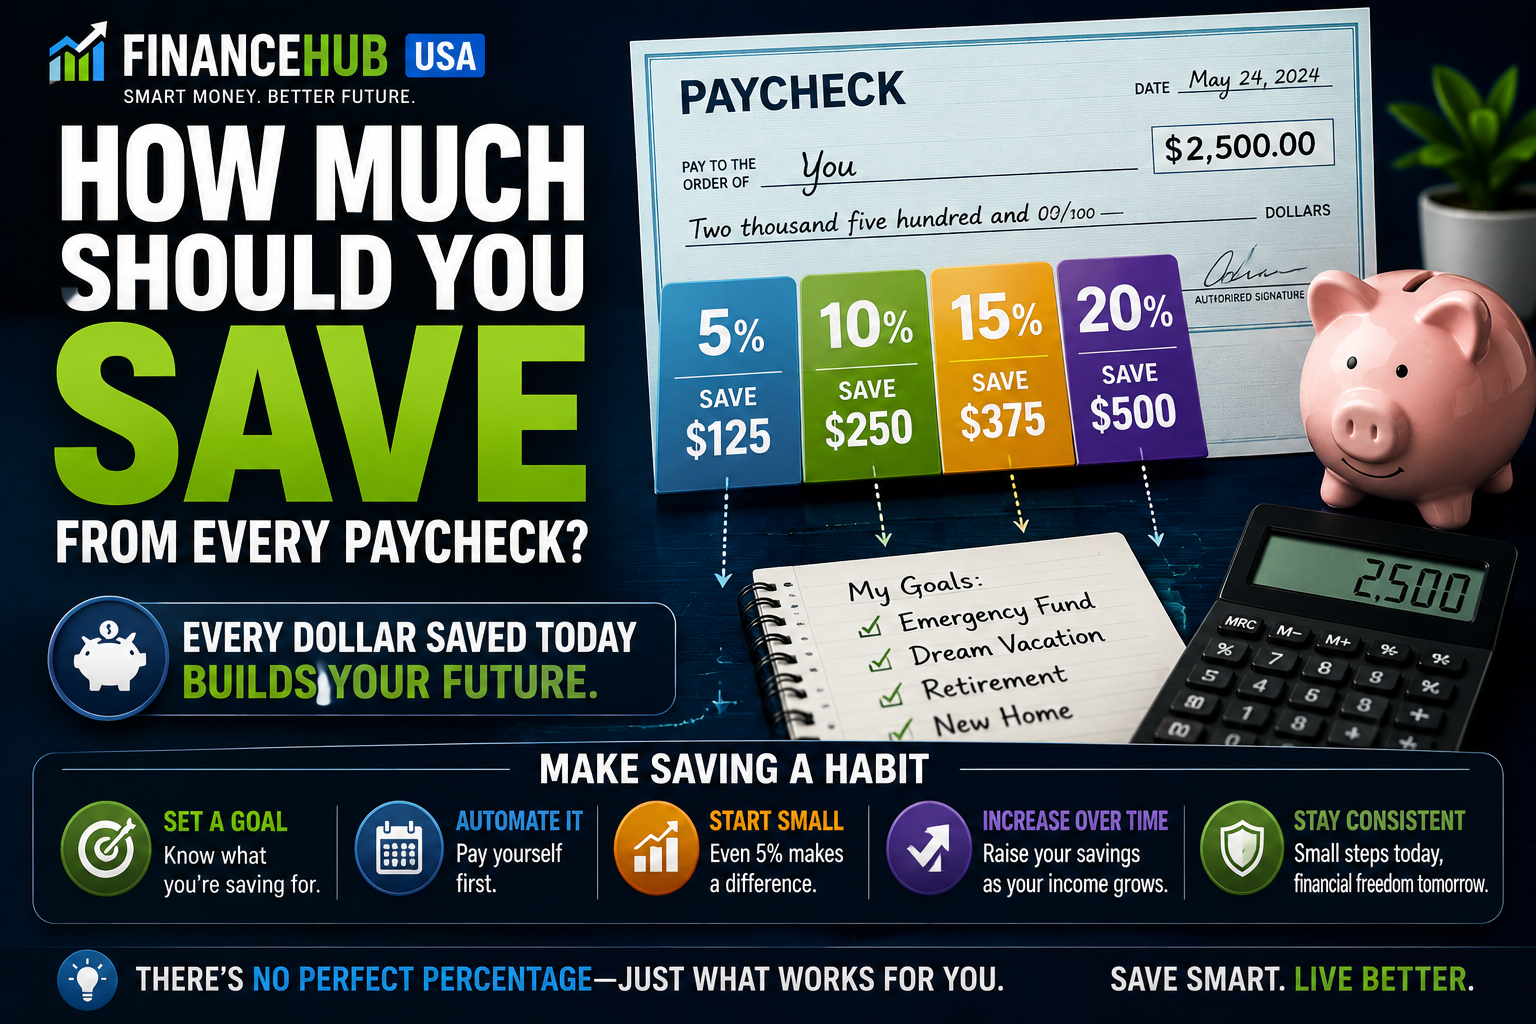
Related reading: How Much Should You Save From Every Paycheck?
Related reading: Should You Save Money or Pay Off Debt First?
Sources and Further Reading
Frequently asked questions
What is the most common budgeting mistake?
The most common mistake is estimating expenses instead of tracking actual spending from bank and credit card statements. I've been guilty of this myself and it always leads to problems.
How much should I save each month?
A common guideline is to save at least 20% of your income, but the right amount depends on your debt, emergency fund, and financial goals. I recommend starting with whatever you can and increasing it over time.
What is a sinking fund in budgeting?
A sinking fund is a separate savings category for predictable future expenses such as car repairs, insurance premiums, holidays, or vacations. I've used this strategy and it's a game-changer.
How often should I review my budget?
I recommend reviewing your budget at least once a month. Compare planned spending with actual spending and adjust for changes in income or expenses. It only takes 15 minutes and it's worth it.
Can budgeting really save thousands of dollars per year?
Yes. Eliminating unused subscriptions, reducing impulse spending, planning for irregular expenses, and paying down high-interest debt can collectively save many households several thousand dollars annually. I've seen this happen with my own finances.