Is It Better to Save Weekly or Monthly?
Is it better to save weekly or monthly? Compare both strategies, see how pay schedules affect saving, and learn how automation can build consistency.
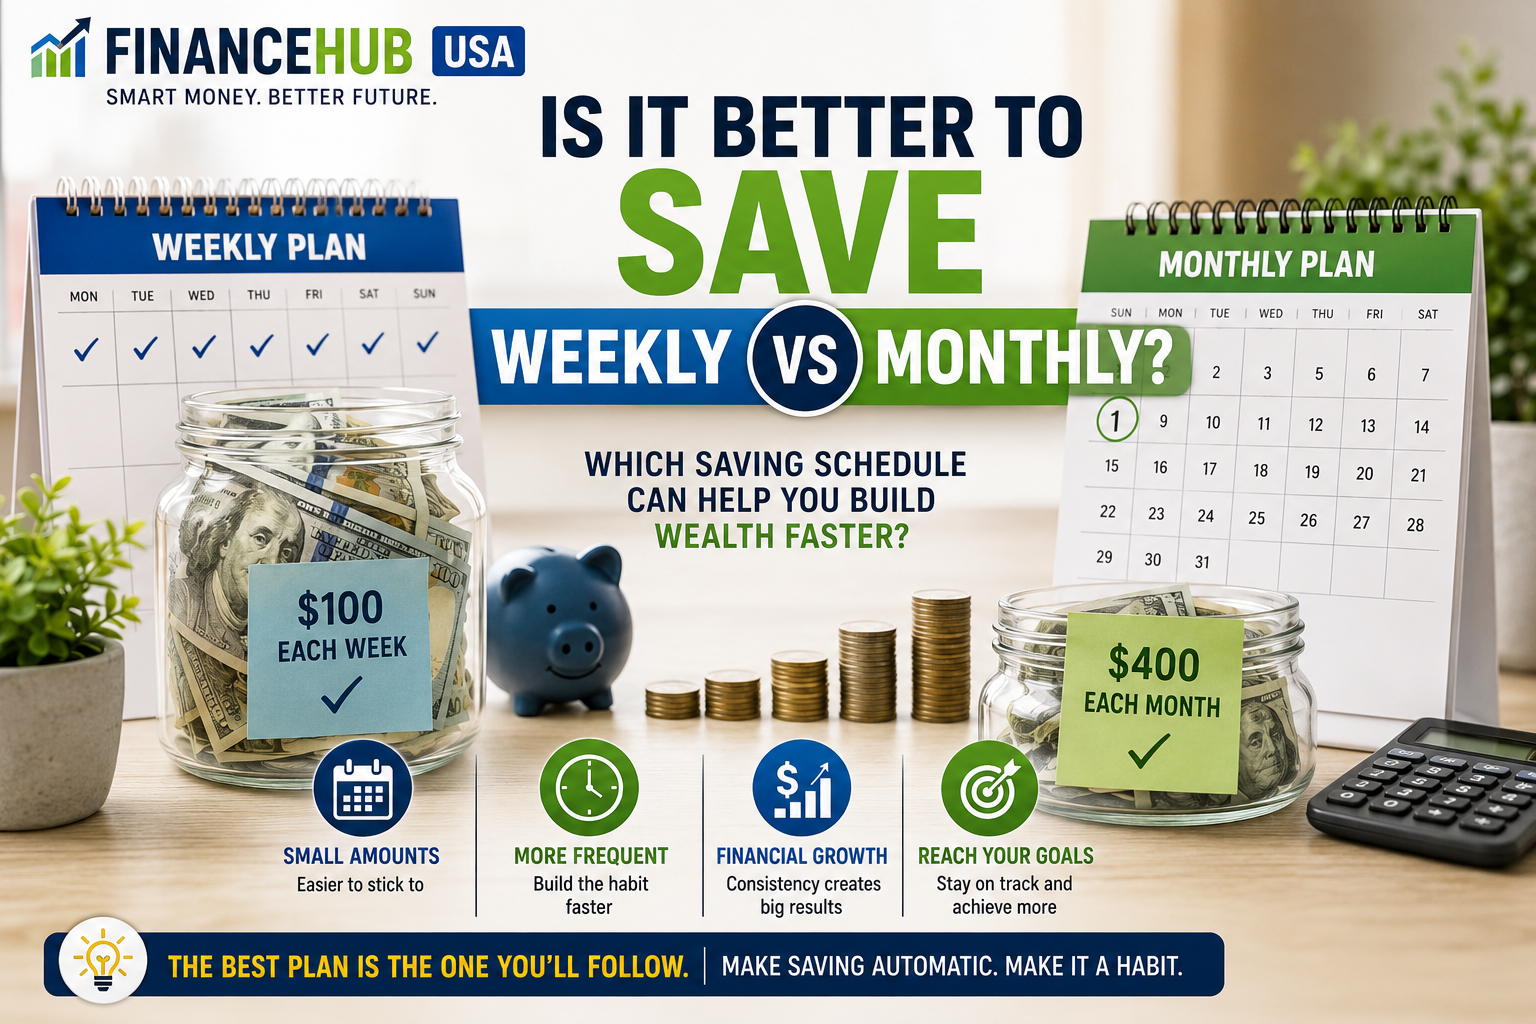

Saving weekly is not automatically better than saving monthly. If the total amount contributed during the year is approximately the same, the financial difference between the two schedules may be relatively small. The more important question is which schedule fits your income and makes it easiest to contribute consistently.
Weekly saving divides a goal into smaller, more frequent transfers. Monthly saving uses fewer, larger contributions. Neither system creates more money simply because of its frequency.
The comparison becomes useful when you account for the calendar correctly. A year has 52 weeks, a typical biweekly payroll has 26 paychecks, a twice-monthly payroll usually has 24, and a monthly schedule has 12. Those differences can materially affect your annual total if the contribution amounts are not adjusted.
Weekly vs. Monthly Saving: What's the Difference?
The main difference is timing. Suppose your goal is to save approximately $5,200 during one year.
| Saving Schedule | Contribution | Contributions Per Year | Approximate Annual Total |
|---|---|---|---|
| Weekly | $100 | 52 | $5,200 |
| Biweekly | $200 | 26 | $5,200 |
| Monthly | $433.33 | 12 | $5,199.96 |
This illustrates the most important rule in a weekly-versus-monthly comparison: compare equivalent annual contributions.
Saving $100 every week produces substantially more money than saving $100 every month, but that is not because weekly saving is inherently superior. It is because one plan contributes $5,200 during the year and the other contributes only $1,200.
Is Saving Weekly Better?
Weekly saving can be useful when your income arrives weekly or when smaller transfers make a large annual goal easier to manage.
For example, a goal of roughly $4,800 per year could feel large when expressed as $400 per month. Dividing the target into weekly contributions would require approximately $92.31 per week.
Advantages of Saving Weekly
- Smaller individual transfers. Dividing a large goal into 52 contributions can make each transfer feel more manageable.
- It can align naturally with weekly income. Someone paid every Friday can make the savings transfer shortly after each paycheck.
- More frequent progress. Weekly contributions create more opportunities during the year to move toward a specific savings target.
- Some deposits arrive earlier. When money reaches an interest-bearing account sooner, those dollars may have additional time to earn interest.
Weekly saving is not automatically easier. Someone paid once per month may find four or five savings transfers during the same month unnecessarily complicated.
Is Saving Monthly Better?
Monthly saving can be simpler for households that already organize their finances around a monthly budget.
Housing, insurance, utilities, subscriptions, and many other expenses are commonly planned monthly, so treating savings as another monthly budget item can make the system easier to understand.
Advantages of Saving Monthly
- Fewer transactions. Twelve annual transfers are easier to monitor than 52.
- Simple annual-goal calculations. A $12,000 annual savings target becomes $1,000 per month.
- It can match monthly income. Workers receiving one major paycheck each month may prefer one savings transfer.
- It fits naturally into monthly budgeting. Saving can be scheduled alongside other recurring obligations.
The main weakness appears when "monthly saving" means waiting until the final day of the month to see what remains. If other spending consumes the money first, the planned contribution may never happen.

Match Your Savings Schedule to Your Pay Schedule
For many households, the most practical answer is to align contributions with when income actually arrives.
| Pay Schedule | Typical Payments Per Year | Possible Contribution Schedule |
|---|---|---|
| Weekly | 52 | After each weekly paycheck |
| Biweekly | 26 | After each biweekly paycheck |
| Twice monthly | 24 | Twice each month |
| Monthly | 12 | After monthly income arrives |
The Consumer Financial Protection Bureau has discussed automatic transfers as one way to make saving more consistent. Some employers may also allow employees to divide direct deposit between accounts.
Automation can reduce the number of decisions required, but it still needs to fit your cash flow. Scheduled transfers should not leave checking without enough money for upcoming bills.
Example: Building a $10,000 Emergency Fund
Imagine Maria wants to build a $10,000 emergency fund over two years. Ignoring interest for simplicity, she needs to contribute approximately $5,000 each year.
| Frequency | Approximate Contribution | Approximate Two-Year Total |
|---|---|---|
| Weekly | $96.15 | $9,999.60 |
| Biweekly | $192.31 | $10,000.12 |
| Monthly | $416.67 | $10,000.08 |
Amounts are rounded and exclude interest, fees, withdrawals, taxes, and changes in income.
The three schedules reach essentially the same goal because their annual contributions are designed to be approximately equivalent.
If Maria receives income weekly, $96.15 each week may fit naturally. If she receives one monthly paycheck, $416.67 per month may be easier to manage.
The schedule changes. The target does not.

Biweekly Is Not the Same as Twice Monthly
This distinction creates one of the most common mistakes when comparing savings schedules.
A person paid twice monthly normally receives 24 paychecks during the year. A person paid biweekly normally receives 26 paychecks because payments occur every two weeks.
| Payroll Schedule | Typical Annual Paychecks | If $200 Is Saved Per Paycheck |
|---|---|---|
| Twice monthly | 24 | $4,800 |
| Biweekly | 26 | $5,200 |
| Difference | 2 paychecks | $400 |
The biweekly saver contributes $400 more because two additional $200 transfers occur during the year.
This is not an investment return and the extra paychecks are not "free money." The worker's annual pay is simply distributed across 26 pay periods instead of 24.
Why Biweekly Workers Sometimes Get Three Paychecks in a Month
Because a biweekly schedule follows a 14-day cycle rather than the calendar month, a worker who normally receives two paychecks during most months will typically encounter two months during the year with three paychecks.
Households that plan recurring expenses around two paychecks per month may decide to use part of those three-paycheck months for an existing financial goal.
But the paycheck should not automatically be treated as surplus. Annual income has not increased merely because of the calendar arrangement, and the money may already be needed for expenses.
What About Months With Five Weeks?
Weekly saving creates a similar calendar effect.
It is common to estimate one month as four weeks, but 12 months multiplied by four weeks equals only 48 weeks. A year normally contains 52 weeks.
That means this comparison is misleading:
| Method | Calculation | Annual Total |
|---|---|---|
| $100 every week | $100 × 52 | $5,200 |
| $400 every month | $400 × 12 | $4,800 |
| Difference | $5,200 − $4,800 | $400 |
Weekly saving appears to "win" by $400, but frequency is not the reason. The weekly saver simply contributed more money.
An approximately equivalent monthly contribution would be $433.33:
$5,200 ÷ 12 ≈ $433.33 per month
Does Saving Weekly Earn More Interest Than Monthly?
It can, but the advantage should not be exaggerated.
If equivalent money reaches an interest-bearing account earlier, some weekly contributions may have additional days to earn interest compared with money that would otherwise be deposited at the end of the month.
However, several factors can matter more:
- The account's APY.
- The total amount contributed.
- Fees or account requirements.
- When during the month the contribution occurs.
- Whether contributions are made consistently.
Timing also changes the comparison. A person depositing the monthly contribution at the beginning of the month could have money earning interest earlier than some of the weekly contributions.
Therefore, there is no universal rule that weekly saving always produces a higher ending balance solely because deposits are more frequent.
FinanceHub USA Analysis: Compare Annual Contributions, Not Transfer Size
The biggest mistake in the weekly-versus-monthly debate is comparing equal transfer amounts instead of equal annual savings amounts.
Consider these two plans:
| Plan | Contribution | Annual Total |
|---|---|---|
| Plan A | $100 weekly | $5,200 |
| Plan B | $100 monthly | $1,200 |
Saying Plan A is better because it ends with more money misses the point. The saver contributed $4,000 more during the year.
A fair comparison starts with the annual goal and works backward:
Annual goal ÷ number of contributions = contribution per period
For a $12,000 annual goal:
| Frequency | Calculation | Approximate Contribution |
|---|---|---|
| Weekly | $12,000 ÷ 52 | $230.77 |
| Biweekly | $12,000 ÷ 26 | $461.54 |
| Twice monthly | $12,000 ÷ 24 | $500 |
| Monthly | $12,000 ÷ 12 | $1,000 |
Once the contributions are normalized this way, the decision becomes much clearer: choose the timing that fits your income and cash flow.
Common Weekly vs. Monthly Saving Mistakes
- Comparing $100 weekly with $100 monthly. Those plans contribute dramatically different annual amounts.
- Assuming four weeks equals one month. Four weeks multiplied by 12 months accounts for only 48 weeks.
- Confusing biweekly with twice monthly. One typically produces 26 paychecks and the other 24.
- Assuming more frequent transfers automatically produce better returns. Contribution amount, APY, and timing also matter.
- Choosing a schedule that does not match cash flow. A mathematically correct plan can still fail if the transfers occur before important bills.
- Waiting until the end of the period to decide whether to save. A planned contribution is generally easier to execute than relying on whatever happens to remain.

So Which Schedule Should You Choose?
| Your Situation | Schedule That May Fit Naturally |
|---|---|
| Paid weekly | Weekly contributions |
| Paid every two weeks | Biweekly contributions |
| Paid twice each month | Twice-monthly contributions |
| Paid monthly | Monthly contribution |
| Prefer smaller transfers | More frequent contributions may feel easier |
| Prefer fewer transactions | Monthly contributions may be simpler |
These are practical illustrations, not rules. Your actual schedule should account for when income arrives, when major bills are due, and how much cash needs to remain available between transfers.
Final Thoughts
So, is it better to save weekly or monthly? Neither frequency automatically wins. When annual contributions are equivalent, the difference usually comes down to timing, convenience, cash flow, and consistency.
Weekly saving can break a large annual goal into smaller pieces. Monthly saving can reduce the number of transfers and fit naturally into a monthly budget.
The most important step is to compare the schedules correctly. Start with the amount you want to save during the year, divide it by the number of contributions, and choose the frequency that best matches when you get paid.
Related reading: How Much Should You Save From Every Paycheck?
Related reading: How Much Money Should You Have Left After Bills?
Sources and further reading:
Frequently asked questions
Is it better to save weekly or monthly?
Neither frequency is automatically better. The strongest schedule is generally the one that matches your cash flow and allows you to save consistently.
Does saving weekly help you save more money?
It can if smaller, frequent contributions help you stay consistent. But weekly saving does not inherently create more money when compared with equivalent monthly contributions.
Does saving weekly earn more interest than monthly?
Depositing equivalent money earlier can potentially produce slightly more interest, but the difference may be modest. Total contributions, APY, fees, and consistency usually deserve more attention.
How much is $100 a week for one year?
Saving $100 for each of 52 weeks produces $5,200 before interest, fees, taxes, or withdrawals.
What is the monthly equivalent of saving $100 per week?
Approximately $433.33 per month produces roughly the same $5,200 annual contribution.
Should I save every time I get paid?
Saving from each paycheck can be an effective strategy because the contribution naturally follows your income schedule and can often be automated.
How many paychecks do you get if you are paid biweekly?
A standard biweekly schedule generally produces 26 paychecks during a 52-week year, although payroll calendars can vary.
Is biweekly the same as twice a month?
No. Biweekly generally means every two weeks and typically results in 26 paychecks per year. Twice monthly generally produces 24 paychecks.
Should people with irregular income save a percentage?
A percentage-based approach can be useful because contributions automatically adjust when income rises or falls. The appropriate percentage depends on individual circumstances.
Should I automate my savings?
Automatic transfers can help make saving consistent. However, you should monitor your checking balance and upcoming expenses to avoid transferring more than your cash flow can support.
Where should I keep my emergency savings?
Emergency savings generally prioritize accessibility and stability. Eligible savings deposits at FDIC-insured banks can receive deposit insurance within applicable limits.
What matters more: how often I save or how much I save?
The amount and consistency of your contributions generally have a larger impact on reaching your goal than choosing weekly instead of monthly deposits.