What Happens If Your Insurance Claim Is Denied?
An insurance claim denial isn't always final. Learn why insurers deny claims, what to review, how to challenge a decision, and which steps to take next.
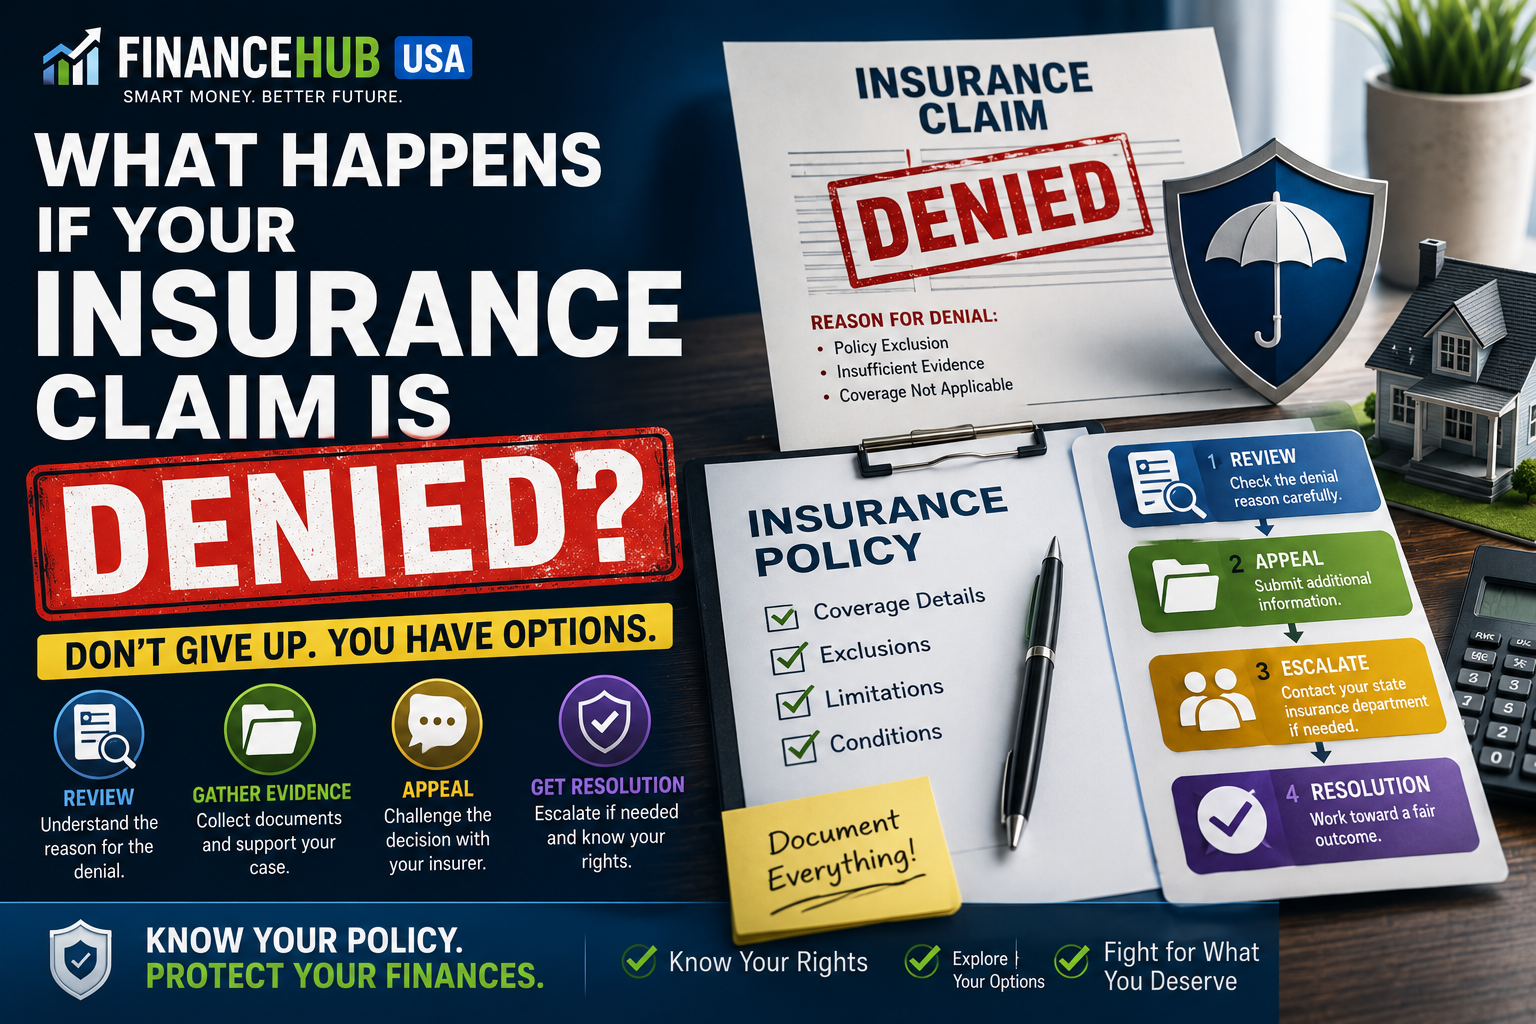
What to Do If Your Insurance Claim Is Denied

Receiving an insurance claim denial can be financially stressful, especially when the claim involves thousands of dollars in medical bills, vehicle repairs, property damage, or stolen belongings.
But the word denied does not necessarily mean the dispute is over or that you automatically have to pay the entire amount yourself.
Insurance claims can be denied for many reasons. Some involve exclusions or genuine coverage limitations. Others involve missing documents, coding mistakes, filing problems, disagreements about what caused the loss, or disputes over how much the insurer should pay.
The most important first step is not to panic or immediately accept the denial. Instead, determine exactly why the insurer denied the claim, compare that explanation with your policy, preserve your evidence, and identify which review or appeal procedures are available.
Why Do Insurance Companies Deny Claims?
Insurance companies evaluate claims according to the terms of the insurance contract and applicable law.
A loss can be real and expensive while still becoming disputed over whether the policy actually covers it.
Common reasons for a denial can include:
- The event is not covered by the policy.
- A specific policy exclusion applies.
- The policy was not active when the loss occurred.
- Required information or documentation is missing.
- The claim was submitted incorrectly.
- The insurer disputes what caused the damage.
- The insurer disputes the amount of the loss.
- A filing or notification deadline was missed.
- A policy requirement was not satisfied.
- A health insurance billing or coding error occurred.
In health insurance, some claim problems can result from administrative issues rather than a final coverage determination. The National Association of Insurance Commissioners notes that issues such as incorrect billing codes or claims submitted to the wrong insurer can contribute to denials or processing problems.
Denied vs. Rejected vs. Partially Approved
These terms are sometimes used interchangeably by consumers, but they can describe different situations.
| Claim Status | General Meaning |
|---|---|
| Denied | The insurer has determined that some or all of the claim will not be covered. |
| Rejected or returned | The claim may not have been properly processed because information was incomplete or incorrect. |
| Partially approved | The insurer accepts part of the claim but disputes or excludes another portion. |
This distinction matters because correcting a missing code may be much easier than challenging a formal coverage exclusion.
Your First Step: Read the Denial Letter Carefully

Do not rely only on what a representative tells you by phone.
Read the written denial alongside:
- Your declarations page
- The full policy
- Endorsements
- Exclusions
- Deductible information
- Coverage limits
- Claim correspondence
Look for the exact policy provision the insurer says supports the denial.
Then ask:
Does the insurer's explanation match both the policy language and what actually happened?
Example: Homeowners Claim Denial
Suppose Rachel experiences $14,000 of storm-related property damage.
The insurer agrees that the property was damaged but denies $8,000 of the claim based on a particular policy provision.
Rachel needs to determine whether the disagreement is about:
- The cause of the damage
- An exclusion
- The amount required to repair the property
- Depreciation
- The deductible
- A coverage limit
A statement such as "claim denied" does not explain which of these issues is actually controlling the decision.
Build a Complete Claim File
Your strongest response is usually built on documentation rather than frustration.
Create one organized file containing everything connected to the claim.
- Save the denial letter. Keep the complete written explanation from the insurer.
- Keep the policy that was in force. Insurance contracts can change from one renewal period to another.
- Save photographs and videos. Document damage before repairs whenever practical and safe.
- Keep receipts and invoices. These may help establish the amount of the loss.
- Keep estimates. Contractor, mechanic, medical, or professional estimates can help support disputed costs.
- Create a communication log. Record dates, names, phone numbers, emails, and what representatives told you.
- Keep proof of submission. Save confirmation that documents and appeals were delivered.
- Track every deadline. Missing a review or appeal deadline can materially affect your options.
Ask the Insurer to Explain the Denial in Writing
If the explanation is unclear, ask for clarification.
Useful questions can include:
- Which policy provision supports the denial?
- Is the entire claim denied or only part of it?
- What additional documentation would change the decision?
- Is there an internal review or appeal process?
- What deadline applies?
- Where should supporting documents be submitted?
A Denial Based on Missing Information May Be Easier to Correct
| Reason Given | What to Review | Possible Response |
|---|---|---|
| Missing documentation | Claim file and insurer request | Submit the missing records |
| Incorrect information | Application, forms, billing codes | Correct the error when appropriate |
| Excluded loss | Policy exclusions and endorsements | Determine whether the exclusion actually applies |
| Disputed repair amount | Adjuster and contractor estimates | Provide competing documentation |
| Coverage limit reached | Declarations and limit provisions | Verify the applicable limit |
What Is an Explanation of Benefits?
For health insurance, an Explanation of Benefits, commonly called an EOB, is especially important.
An EOB generally explains:
- The amount billed by the provider
- The plan's allowed amount
- The amount the insurer paid
- The amount applied to your deductible
- Copays or coinsurance
- The amount the plan says you may owe
- Reasons for denied or reduced payment
An EOB is generally not itself a bill.
Compare it with any bill received from the health care provider before paying a disputed amount.
Health Insurance Claim Denied Because of a Coding Error
Medical claims contain billing codes describing diagnoses, procedures, services, and treatment.
If the wrong code is submitted, the insurer may deny or incorrectly process the claim.
If you suspect a coding issue:
- Contact the provider's billing department.
- Ask whether the claim was coded correctly.
- Compare the provider bill with the EOB.
- Ask whether the claim can be corrected and resubmitted.
A corrected claim can sometimes resolve the problem without requiring a full appeal.
How Do You Appeal an Insurance Claim Denial?
Once you understand the stated reason and have supporting evidence, follow the review procedure provided by your insurer and applicable law.
A strong appeal should directly respond to the insurer's reasoning.
Instead of writing only:
"I think this denial is unfair."
Explain:
- Which part of the decision you dispute
- Which policy language you believe applies
- Which evidence supports your position
- What outcome you are requesting
Example of a Stronger Appeal Argument
Suppose an insurer says water damage resulted from long-term maintenance problems and is therefore excluded.
You believe the damage resulted from a sudden covered plumbing failure.
Your supporting documentation could include:
- Photos of the failed pipe
- A plumber's written findings
- Repair invoices
- Maintenance records
- The relevant policy language
The appeal should connect those facts directly with the disputed coverage decision.
Your State Department of Insurance May Be Able to Help
If you have tried to resolve the problem with the insurer and remain dissatisfied, you may be able to submit a complaint to your state Department of Insurance.
The NAIC explains that state insurance departments can investigate complaints involving issues such as:
- Unfair claim delays
- Unfair denials
- Failure to honor policy terms
- Possible violations of state insurance law
- Lack of timely communication
- Potentially improper cancellation or nonrenewal
State processes vary, but complaints are generally handled by the insurance regulator in the state with jurisdiction over the policy or insurer.
What Should You Include in a State Insurance Complaint?
Prepare:
- Your policy number
- Claim number
- Denial letter
- A clear timeline
- Bills and estimates
- Photographs where relevant
- Emails and letters
- Communication records
- Copies of appeal submissions
The NAIC recommends creating detailed records of communication and gathering relevant bills and documentation before filing a complaint. :contentReference[oaicite:3]{index=3}
What a State Department of Insurance Cannot Necessarily Do
A regulator complaint can be useful, but it is not the same thing as a court judgment.
A state insurance department may investigate whether an insurer followed applicable insurance laws and policy requirements.
However, the regulator may not be able to:
- Resolve every contractual dispute
- Determine disputed factual issues requiring litigation
- Award every type of damages available through a court
- Provide personal legal representation
For significant disputes, consumers may decide to obtain legal or professional advice appropriate to the type of claim and state law.
Health Insurance Has Specific Appeal Rights

Health insurance claims require separate attention because many plans are subject to specific internal and external appeal protections.
HealthCare.gov explains that consumers can request an internal review when a health plan refuses to pay for or provide a service they believe should be covered.
Internal Health Insurance Appeal Deadline
Under the federal process described by HealthCare.gov, you generally have 180 days from receiving notice of the denial to file an internal appeal.
The plan's actual notice should explain how and where to submit the appeal.
What to Include With a Health Insurance Appeal
HealthCare.gov recommends keeping records such as:
- The EOB
- The denial letter
- The appeal request
- Medical records
- Letters from doctors
- Other supporting medical evidence
- Notes from conversations with the insurer and provider
A physician's statement can be particularly useful when the insurer disputes medical necessity.
How Long Can an Internal Health Appeal Take?
HealthCare.gov states that internal appeals generally must be completed within:
| Situation | General Federal Timeline |
|---|---|
| Service not yet received | Within 30 days |
| Service already received | Within 60 days |
Urgent cases may qualify for faster review procedures.
Urgent Health Insurance Appeals
If waiting through the normal appeal process could seriously jeopardize your life, health, or ability to regain maximum function, expedited procedures may be available.
HealthCare.gov states that consumers with qualifying urgent situations may be able to request an external review while an internal appeal is still underway. :contentReference[oaicite:4]{index=4}
What Is an External Review?
An external review takes the disputed health coverage decision outside the insurance company.
An independent reviewer evaluates the case.
If the external reviewer overturns the insurer's decision, the insurer is generally required to accept that determination.
External review may apply to eligible denials involving issues such as:
- Medical necessity
- Appropriateness of treatment
- Level of care
- Experimental or investigational treatment
- Certain coverage rescissions
External Review Deadline
HealthCare.gov states that a written external review request generally must be filed within four months after receiving the relevant final denial or determination.
A standard external review is generally decided no later than 45 days after the request is received.
Qualifying expedited external reviews are generally decided no later than 72 hours, or sooner when medically necessary. :contentReference[oaicite:5]{index=5}
Important 2026 Federal External Review Update
HealthCare.gov currently notes an important 2026 exception.
As of July 1, 2026, the HHS-administered Federal External Review Process is temporarily unavailable for certain plans or issuers using that federal process in:
- Alabama
- Florida
- Georgia
- Texas
- Wisconsin
- Certain U.S. territories
HealthCare.gov advises affected consumers to review instructions from their plan or issuer and states that HHS is working on a solution and additional guidance regarding deadlines.
Because this situation can change, consumers should verify the current instructions on HealthCare.gov and in their denial notice before submitting an external review request. :contentReference[oaicite:6]{index=6}
Example: $20,000 Medical Claim
Suppose Michael receives treatment that generates a $20,000 health insurance claim.
The insurer denies coverage because it considers one part of the treatment not medically necessary.
Michael should not automatically assume he now owes $20,000.
He can:
- Review the EOB.
- Read the denial explanation.
- Review his plan documents.
- Talk with the provider.
- Ask for supporting clinical records.
- Submit an internal appeal if eligible.
- Consider external review if the dispute qualifies.
The final amount Michael owes may also differ from the original $20,000 billed amount because of negotiated rates, partial coverage, cost sharing, or corrections.
Do Not Assume the Provider's Original Bill Is Your Final Responsibility
This is particularly important with medical insurance.
Suppose:
- Hospital bill: $20,000
- Insurer-negotiated allowed amount: $11,000
The original $20,000 charge does not automatically mean the patient owes $20,000 after a denial.
The final financial responsibility depends on the plan, network rules, claim status, appeal outcome, and applicable laws.
What If an Auto Insurance Claim Is Denied?
Auto claim disputes often involve questions about:
- Who caused the accident
- Whether the policy was active
- Whether the driver was covered
- Whether a particular coverage applies
- The amount of vehicle damage
- The value of a totaled vehicle
- Policy exclusions
Review the denial alongside:
- Police reports
- Photos
- Repair estimates
- Witness information
- Your declarations page
- The policy
What If a Homeowners Claim Is Denied?
Homeowners disputes can become highly dependent on the cause of damage.
For example, two claims involving water damage may receive very different treatment if one resulted from a sudden plumbing failure and another resulted from long-term deterioration or a type of water loss excluded by the policy.
Useful evidence can include:
- Photos before and after the loss
- Contractor reports
- Plumber reports
- Maintenance records
- Receipts
- Property inventories
- Independent estimates
Should You Make Emergency Repairs Before the Claim Is Resolved?
Sometimes waiting for a dispute to end is not practical.
A leaking roof, broken window, damaged plumbing system, or unsafe vehicle condition can worsen if ignored.
Policies may also require policyholders to take reasonable steps to prevent additional damage.
Before making major permanent repairs when possible:
- Document the original damage thoroughly.
- Notify the insurer.
- Ask what emergency repairs are permitted.
- Keep damaged materials when practical and safe.
- Keep receipts and invoices.
Do not put yourself or others in danger simply to preserve evidence.
What If the Insurer Approves Only Part of the Claim?
You may not have to choose between accepting everything or receiving nothing.
Some claims contain both undisputed and disputed portions.
Example
Suppose a homeowners insurer agrees that $9,000 of a $14,000 loss is covered but disputes another $5,000.
| Amount | |
|---|---|
| Total claimed loss | $14,000 |
| Insurer accepts | $9,000 |
| Amount still disputed | $5,000 |
Ask whether the undisputed amount can be paid while the remaining portion is reviewed.
FinanceHub USA Analysis: A Denial Is Also a Cash Flow Problem

Insurance is a form of financial risk transfer.
You pay premiums so that certain large covered losses do not have to come entirely from your own savings.
A disputed claim temporarily shifts more of that financial risk back to the household.
That means you need to manage two problems at the same time:
- The insurance dispute
- The temporary cash flow risk
Example: $12,000 Auto Repair Claim
Suppose two drivers each face $12,000 of vehicle damage.
Driver A's claim is approved.
Driver B's claim is denied and enters an appeal process.
Driver B may suddenly need to think about:
- Emergency savings
- Temporary transportation
- Repair costs
- Loan payments
- Rental costs
- Possible borrowing
Even if Driver B ultimately wins the dispute, the timing of the reimbursement still matters.
Do Not Assume You Will Definitely Win the Appeal
An appeal can reverse an incorrect denial, but success is never guaranteed.
While challenging the decision, calculate the amount you might have to absorb if the denial remains in place.
This helps prevent a second financial problem.
Avoid High Interest Debt When Possible
A denied claim can create pressure to use credit cards or personal loans immediately.
Before taking expensive debt, determine whether:
- An appeal is pending
- An undisputed payment is available
- The provider or repair company offers payment arrangements
- The expense can be delayed safely
- Emergency savings can cover part of the amount
A temporary insurance dispute can become much more expensive if it creates years of high interest debt.
Should You Hire a Lawyer?
Not every claim denial requires an attorney.
For a simple missing document or billing problem, the insurer or provider may be able to correct the issue directly.
Professional legal advice may deserve consideration when:
- The financial amount is substantial
- The policy language is highly disputed
- The insurer alleges fraud or misrepresentation
- A lawsuit has been threatened or filed
- The claim involves serious injury
- You believe state insurance laws may have been violated
- Important filing deadlines are approaching
The appropriate professional resource depends on the type of insurance and your state.
What About a Public Adjuster?
In some property insurance disputes, consumers may consider hiring a licensed public adjuster.
A public adjuster generally represents the policyholder rather than the insurance company in evaluating and negotiating certain property claims.
Rules, licensing requirements, and fees vary by state.
Before hiring one:
- Verify licensing
- Understand the fee structure
- Read the contract carefully
- Check cancellation rights
- Understand exactly which services will be provided
Watch for Insurance Claim Scams
Large disasters and denied claims can attract contractors, adjusters, or other businesses promising guaranteed insurance payouts.
Be cautious of anyone who:
- Guarantees the insurer will pay
- Pressures you to sign immediately
- Asks you to sign over claim benefits without explanation
- Refuses to provide licensing information
- Requests suspicious upfront payments
Claim Denial Action Plan
| Stage | Action |
|---|---|
| 1 | Read the denial and identify the exact reason |
| 2 | Compare the explanation with the policy |
| 3 | Organize evidence and documentation |
| 4 | Correct administrative errors where applicable |
| 5 | Request reconsideration or file the appropriate appeal |
| 6 | Track every deadline |
| 7 | Consider state regulator assistance if unresolved |
| 8 | Prepare financially in case some amount remains your responsibility |
Common Mistakes After an Insurance Claim Is Denied
- Assuming the first denial is automatically final. Review available appeal or correction procedures.
- Arguing without reading the policy. The contract language is central to many coverage disputes.
- Relying only on phone calls. Keep written records.
- Missing appeal deadlines. Some deadlines can be strict.
- Throwing away damaged property immediately. Preserve evidence when practical and safe.
- Assuming the original billed amount equals final responsibility. Particularly in medical claims, this can be incorrect.
- Taking expensive debt before understanding the claim status. Review all available financial options first.
- Assuming every type of insurance uses the same appeal process. Auto, homeowners, health, life, and other insurance products can follow different rules.
FinanceHub USA Framework: Five Questions After a Denial
| Question | Why It Matters |
|---|---|
| Why exactly was the claim denied? | Determines what evidence or argument matters |
| What does the policy actually say? | Identifies the contractual basis of the dispute |
| What deadline applies? | Protects appeal and review rights |
| What evidence supports my position? | Strengthens a reconsideration or appeal |
| What happens financially if I lose? | Helps prepare for possible out-of-pocket responsibility |
Final Thoughts
An insurance claim denial can be frustrating, but it should usually trigger investigation rather than immediate surrender.
Start by identifying the exact reason for the denial.
Then:
- Review your policy
- Organize your evidence
- Correct administrative errors when possible
- Request clarification in writing
- Follow the insurer's appeal procedure
- Monitor all deadlines
- Consider state regulator assistance if appropriate
Health insurance consumers may have additional internal and external appeal rights. Under the federal process described by HealthCare.gov, internal appeals generally must be filed within 180 days, while qualifying external review requests generally have a four month filing window. Current 2026 federal external review procedures should be verified because temporary administrative changes are affecting certain jurisdictions.
Most importantly, treat the claim as both an insurance issue and a financial planning issue.
Prepare for the possibility that some amount could remain your responsibility while pursuing every legitimate review option available.
The goal is not simply to challenge every denial. It is to understand whether the insurer's decision matches the policy and the facts, preserve your rights, and protect your finances while the dispute is resolved.
Continue exploring FinanceHub USA for practical guides covering insurance, credit, debt, banking, investing, taxes, and personal finance.
Related reading: Insurance Premium vs Deductible Explained
Related reading: Liability vs Full Coverage Car Insurance
Sources and Further Reading
Frequently asked questions
Is an insurance claim denial final?
Not necessarily. Depending on the insurance type, policy and state rules, you may be able to request reconsideration, file an appeal, provide additional documentation, pursue an external review in eligible health insurance cases, or contact your state insurance regulator.
What should I do first if my insurance claim is denied?
Read the written denial carefully and identify the insurer's specific reason. Compare that explanation with your policy and gather documents that could support your position before challenging the decision.
Can I appeal an insurance claim denial?
Appeal and dispute rights depend on the type of insurance, your policy and applicable law. Health insurance plans can have formal internal and external review procedures, while property and auto insurance disputes may follow different state and policy-specific processes.
Can I complain to my state insurance department?
Yes. State insurance departments can accept complaints about insurers, including certain disputes involving claim denials, delays, policy compliance and communication. The department's authority and process vary by state.
How long do I have to appeal a denied health insurance claim?
Under the federal health insurance appeal process described by HealthCare.gov, an internal appeal generally must be filed within 180 days of receiving notice of the denial. Check your denial notice and plan documents because the rules applicable to your specific coverage matter.
What is an external review for health insurance?
An external review allows an eligible health insurance coverage dispute to be reviewed by an independent third party rather than leaving the final decision solely with the insurer.
What evidence can help challenge a denied claim?
Useful evidence depends on the claim but can include the policy, denial letter, photographs, receipts, repair estimates, invoices, medical records, provider letters and a detailed record of communications with the insurer.
Does filing a complaint guarantee my claim will be paid?
No. An appeal, complaint or external review does not guarantee that a denial will be reversed. The outcome depends on the policy, facts, supporting evidence and applicable insurance rules.